Indonesia’s credit risk premium rises as investors weigh MSCI proposal
Economists linked the increase to uncertainty over Indonesia’s market classification and global pressures, while cautioning that it does not signal a default crisis.
Indonesia’s five-year credit default swap (CDS) reached 106.34 on 27 October 2026, compared with 91.78 on 14 October, according to market data cited by CNBC Indonesia. The measure of credit protection costs has remained above 100 since 22 October.
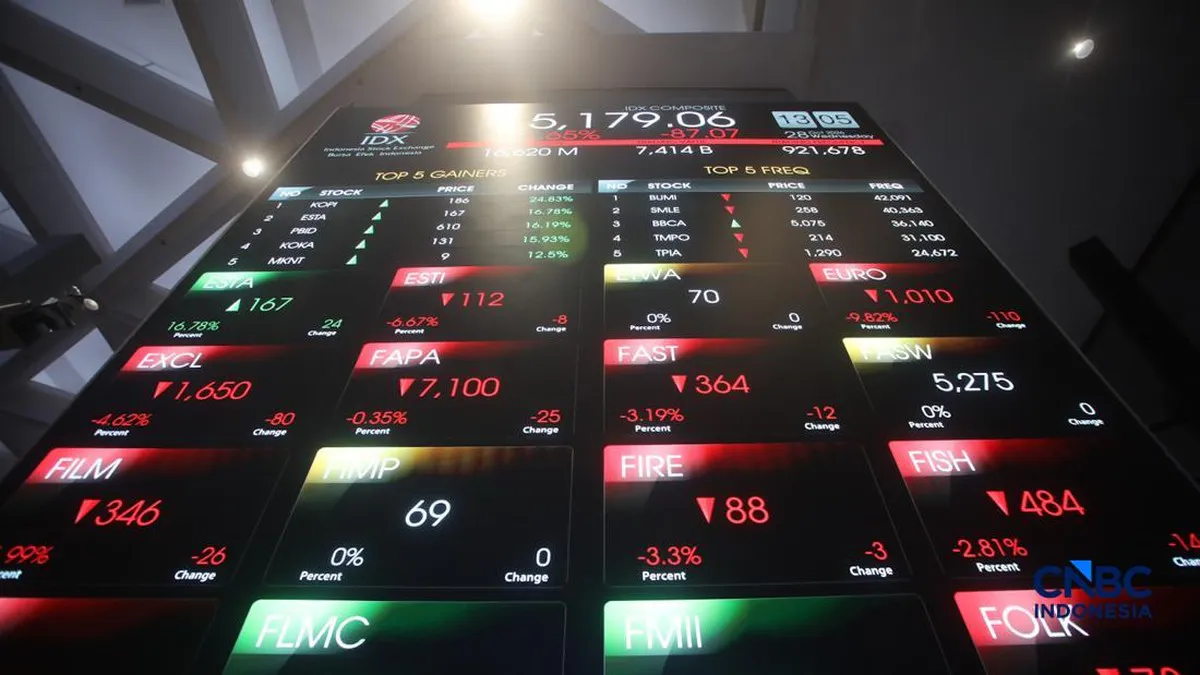
BCA chief economist David Sumual attributed the rise partly to investor concerns about MSCI. On 15 October, MSCI began consulting on a proposal to reclassify Indonesia’s stock market from emerging market to standalone market.
Sumual said elevated oil prices amid worsening conflict in the Middle East were also unsettling Indonesia’s bond market. He warned that higher credit risk premiums could push up government bond yields and put further pressure on the rupiah against the US dollar.
Permata Bank chief economist Josua Pardede said global pressures and domestic uncertainty were prompting investors to seek greater compensation for holding Indonesian assets. He cited US 10-year Treasury yields of around 5% and a rupiah approaching Rp18,200 per US dollar among the pressures.
Pardede said Indonesia’s 10-year government bond yield reached around 7.62% on 28 October, about 48 basis points higher than at the end of September. Total bids at the 27 October government bond auction fell about 52% from the auction two weeks earlier, which he said indicated increasingly selective demand.
Nevertheless, foreign investors recorded net purchases of around US$480 million in government securities during October, according to Pardede. He said the yield increase reflected repricing for greater risk rather than a loss of confidence among all investors.
Pardede also cautioned against interpreting higher CDS levels as evidence of a default crisis. Indonesia retained an investment-grade credit rating and foreign exchange reserves of around US$146.3 billion, he said, adding that further increases in bond yields were not inevitable.