SGX daily derivatives volume reaches six-month high in October
Securities turnover reached S$44.8 billion, up 32 per cent from a year earlier, as trading increased during a market correction.
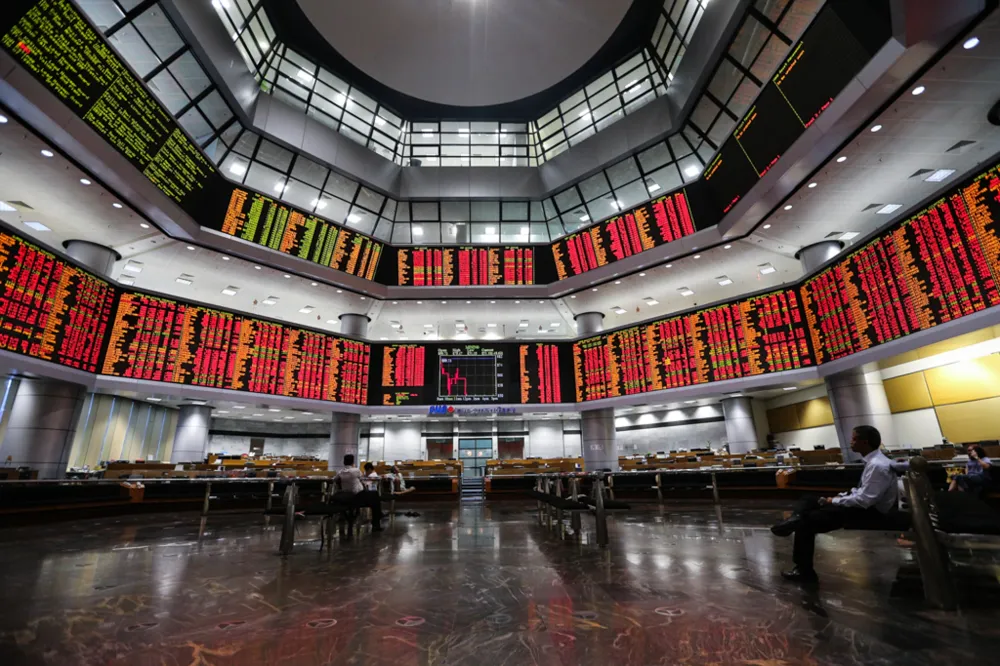
Singapore Exchange (SGX) reported an October daily average of 1.6 million derivatives contracts, the strongest since April. The exchange operator said on Nov 12 that increased market volatility had lifted demand for risk management.
The daily average was 8 per cent above a year earlier and 17 per cent higher than September. Overall derivatives volume reached 31.4 million contracts, representing annual growth of 6 per cent and a monthly increase of 5 per cent.
Across 22 trading days, securities turnover totalled S$44.8 billion, rising 32 per cent from a year earlier and 6 per cent from September. Daily average securities value reached S$2 billion, with SGX attributing the increased activity to index stocks and real estate investment trusts.
The gains in trading coincided with a broader market correction led by technology shares. The Straits Times Index closed October at 5,376.74, a decline of 5 per cent from September’s closing level of 5,675.88. It remained 21 per cent above its year-earlier level.
FTSE China A50 Index Futures averaged 660,868 contracts daily, a 24-month high. SGX maintained continuous liquidity during China’s Golden Week holiday, which ran from Oct 1 to 7. Open interest in the contract rose 25 per cent from September to about one million contracts.
Foreign exchange derivatives volume reached 8.5 million contracts, up 27 per cent from a year earlier. US dollar/offshore yuan futures averaged 190,000 lots daily, an annual increase of 16 per cent, while the daily average for Indian rupee/US dollar futures rose 40 per cent to 196,421 lots.